Executive Overview of the Convenience, Mom And Pop Stores Market
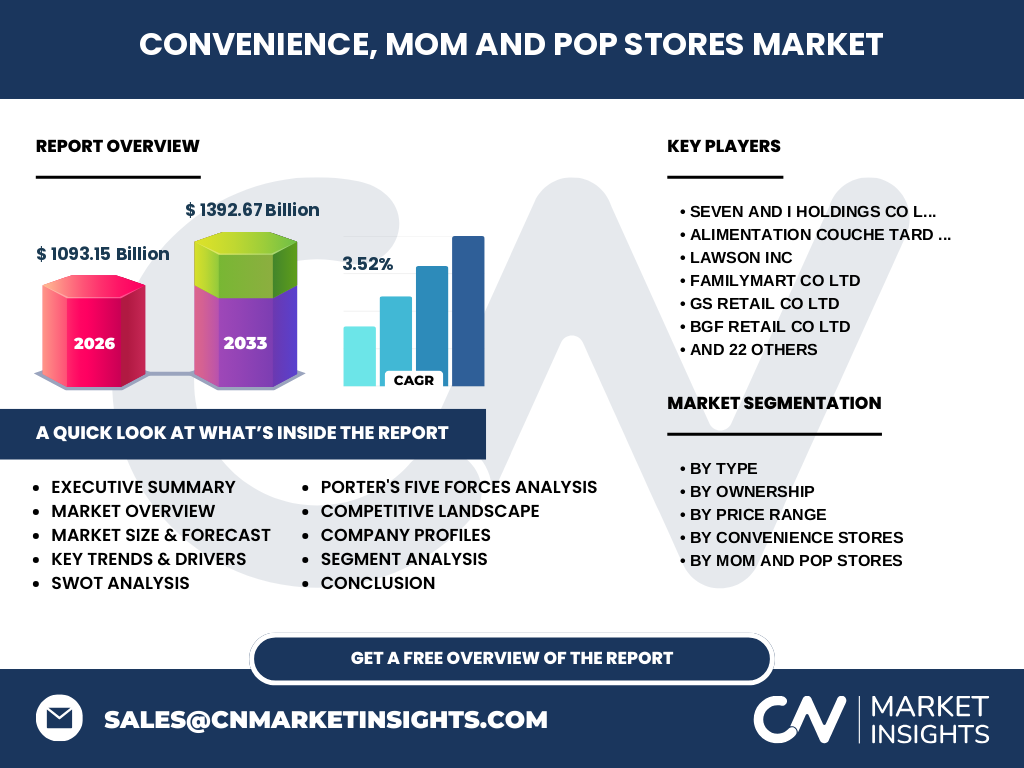
The Convenience, Mom And Pop Stores Market is a fundamental retail pillar, valued at $1093.15 Billion in 2026. Our analysis reveals that these outlets serve as essential community hubs, bridging the gap between hypermarket efficiency and hyper-local accessibility. With a projected expansion to $1392.67 Billion by 2033, the sector remains resilient, driven by unmatched proximity and the evolving integration of high-margin essential services within neighborhood landscapes.
Structural Growth Drivers and Market Constraints
Growth is primarily fueled by urban density and the demand for instant gratification. Key constraints include supply chain fragmentation and rising operational costs due to labor shortages. However, opportunities abound in digital transformation and SKU optimization. Retailers must navigate complex regulatory environments like the FDA’s Food Safety Modernization Act or regional licensing hurdles that complicate inventory procurement for independent owners.
Emerging Trends Reshaping Retail Proximity
The sector is witnessing a pivot toward quick-commerce integration and private-label expansion. Players like Zabka Polska are setting benchmarks in automated checkout, while others prioritize fresh-food-to-go solutions. This trend favors retailers who leverage real-time inventory data to minimize waste, a critical hurdle for mom-and-pop shops traditionally reliant on manual stock management, effectively bridging the gap between local charm and digital precision.
Impact of COVID-19 on Neighborhood Retail Recovery
The pandemic acted as a catalyst for local resilience, forcing a rapid shift toward delivery-first models. While initial disruptions caused significant inventory shrinkage, recovery has been marked by an increased reliance on local neighborhood shops over centralized malls. Strategic agility during this period allowed companies like 7-Eleven to capture increased market share, demonstrating the enduring necessity of hyper-local retail nodes during global supply chain volatility.
Competitive Landscape and Strategic Dynamics
Market concentration is bifurcated between global giants like Seven and i Holdings and Alimentation Couche-Tard and a vast, fragmented base of independent retailers. Strategic dynamics center on operational scale, with chain operators aggressively deploying proprietary supply chain tech to optimize margins, while independent players focus on curated assortments that resonate with localized demographics, often shielded by unique neighborhood loyalty networks.
Market Forecast 2027 to 2033
The Convenience, Mom And Pop Stores Market is projected to achieve a CAGR of 3.52%, reaching a valuation of $1392.67 Billion by 2033. This steady trajectory reflects a fundamental shift toward convenience-centric consumer behavior. Future gains will be gated by a firm's ability to integrate fintech payment solutions and manage logistics within constrained urban environments where last-mile efficiency determines profitability.
Segmentation Analysis of the Retail Landscape
We categorize the market by Type (Convenience vs. Mom and Pop), Ownership (Retail Chain vs. Independent), and Price Range (Premium to Economy). This segmentation highlights the role of Gas Station Convenience Stores as high-traffic hubs, contrasting with Family-Owned Retailers that specialize in community-specific goods. Each segment requires distinct logistical strategies to manage inventory, ranging from bulk distribution for chains to localized wholesale procurement for neighborhood units.
Regional Market Performance and Geographic Trends
Performance varies significantly by region, with Asia-Pacific demonstrating intense concentration in chain-led convenience formats, while Europe sees robust activity in SPAR International and Tesco PLC driven convenience models. Regional growth is dictated by local zoning laws and urban density. Our data suggests that emerging economies provide the highest growth potential, provided retailers can overcome infrastructure hurdles related to cold-chain cold-storage access.
In-depth Review of Global Key Players
Leading players like Lawson Inc, FamilyMart, and GS Retail demonstrate strategic mastery in inventory velocity. Conversely, Wawa Inc and QuikTrip exemplify the fuel-to-food revenue pivot in North America. These companies utilize massive logistical infrastructure to maintain price competitiveness. Their ability to innovate, such as integrating micro-fulfillment centers, distinguishes them from smaller, local participants who prioritize personalized customer engagement in their business models.
Porter's Five Forces Assessment
The threat of new entrants is moderate, mitigated by high capital intensity and zoning barriers. Buyer power is high, given the ubiquitous nature of products sold. Competitive rivalry remains intense, as major players like Carrefour SA and X5 Retail Group aggressively expand their footprint. Supply chain hurdles, specifically for fresh produce and perishables, continue to act as a significant constraint for independent store owners in this space.
SWOT Analysis of the Sector
Strengths: High accessibility and brand loyalty. Weaknesses: Thin profit margins and vulnerability to supply shocks. Opportunities: Digital integration, automated retail, and expansion of fresh-prepared foods. Threats: Increasing labor costs and regulatory burdens imposed by local authorities. Our analysis indicates that players failing to digitize their inventory management systems will face significant erosion of their competitive position against tech-enabled retailers by 2030.
Value Chain and Operational Flow
The value chain begins with raw material procurement from agricultural suppliers, moving through regional wholesale distribution hubs, and finally to the end consumer. For independent retailers, this flow is often interrupted by localized logistical hurdles. Corporate retail chains mitigate these risks via vertically integrated supply networks, ensuring consistent stock availability even during periods of global logistics congestion or increased regulatory oversight.
Investment Insights and High-Potential Strategies
Investment focus should prioritize tech-enabled retail platforms and last-mile delivery optimization. High-potential areas include automated, 24/7 convenience kiosks and retailers capable of implementing personalized loyalty programs. Investors should target companies that effectively balance operational efficiency with a deep understanding of local market idiosyncrasies, as this combination is the primary driver of long-term asset appreciation within the global convenience store landscape.
Research Methodology for Baseline Estimates
Our estimates are derived from a rigorous triangulation process, combining public trade registry data, proprietary primary stakeholder interviews with retail executives, and macroeconomic indicators from bodies like the World Bank. We account for regional regulatory nuances and sector-specific inflationary pressures to provide a granular forecast. This dual-layer approach ensures our $1093.15 Billion valuation reflects actualized market activity rather than mere aggregate trends.
Scope and Strategic Limitations
This analysis covers the global Convenience, Mom And Pop Stores Market, including both chain-owned and independent retail units. The scope excludes large-scale hypermarkets and warehouse clubs. While our data provides a comprehensive outlook, limitations include potential volatility in local currency fluctuations and unforeseen shifts in national trade policies that may affect the procurement of imported specialty food items within specific regions.
Recent Developments and Market Moves
Recent strategic moves emphasize M&A activity to consolidate prime real estate. For example, Alimentation Couche-Tard continues to leverage its global scale to acquire regional assets, while EG Group focuses on diversifying its retail food offering. These announcements suggest a market-wide trend toward integrated service hubs, where traditional convenience is being augmented by digital financial services and high-demand, ready-to-eat premium grocery solutions.